ITC denied for delayed filing under Section 16(4), but returns were filed before 30.11.2021—Kerala High Court directed the Department to reconsider and grant ITC under Section 16(5), if otherwise eligible.
Issue:
Whether the Department was justified in denying Input Tax Credit to the Assessee under Section 16(4) of the CGST Act when the returns for January 2019 and February 2019 had been filed before 30.11.2021, thereby satisfying the conditions prescribed under Section 16(5).
Rule:
Section 16(5) of the CGST Act grants a special enabling benefit allowing Input Tax Credit where the prescribed returns were furnished on or before 30.11.2021, notwithstanding the limitation contemplated under Section 16(4), subject to fulfilment of other statutory conditions.
Application:
The Assessee had claimed Input Tax Credit for January 2019 and February 2019. The Department rejected the claim solely on the ground that the returns were filed beyond the time limit under Section 16(4). However, the Court found that the returns had actually been filed on 11.01.2020, which was well before the cut-off date of 30.11.2021 prescribed under Section 16(5). Consequently, the Court held that the denial of ITC solely by invoking Section 16(4) was unsustainable.
Conclusion:
The High Court of Kerala quashed the impugned order and directed the Department to reconsider the Assessee's claim and grant Input Tax Credit in accordance with Section 16(5) of the CGST Act, subject to fulfilment of all other statutory conditions.
Impact Analysis:
This judgment reiterates that the benefit of Section 16(5) overrides the limitation under Section 16(4) where the statutory conditions are satisfied. It strengthens the right of eligible taxpayers to claim ITC if returns were filed on or before 30.11.2021, despite earlier denial based solely on limitation.
Title: POOTHANKARA ANOOPKUMAR vs. SUPERINTENDENT
Court: THE HIGH COURT OF KERALA
Citation: WP(C) NO. 15526 OF 2026
Dated: 22-05-2026
Provision: Under Section 16(4), 16(5)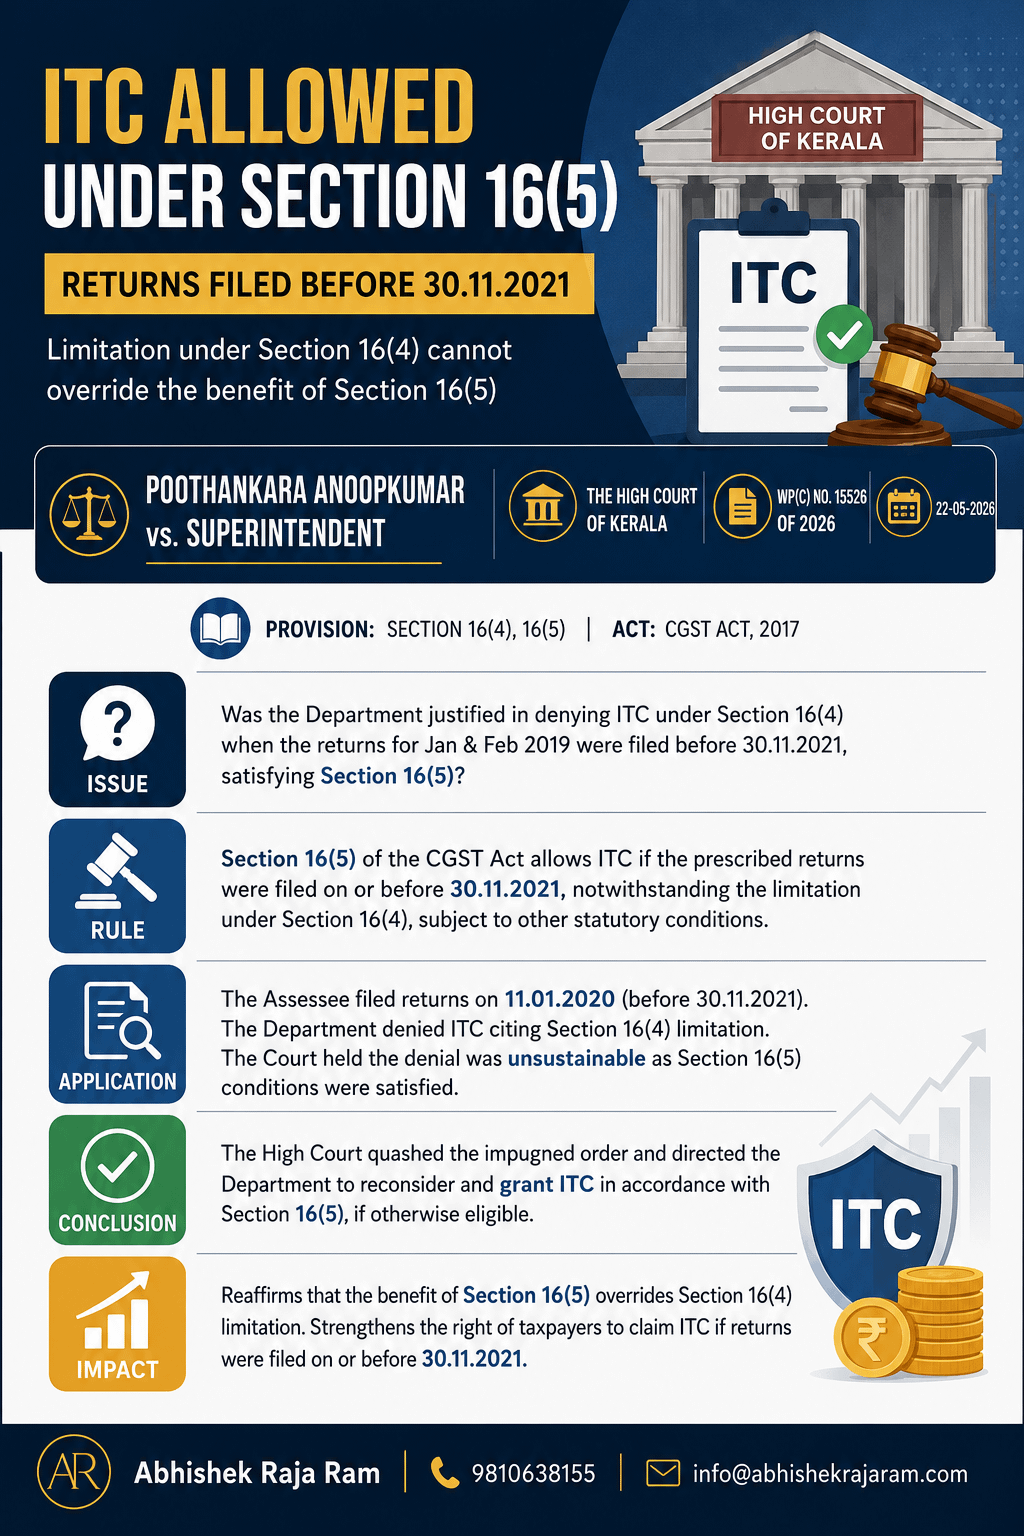
Abhishek Raja "Ram"
@abhishekrajaram
MEC, STBA Delhi || Speaker and Author on GST. Life dedicated towards Tax and Economic Reforms & Simplification